The Insurance Development and Regulatory Authority has instructed all insurance companies in Bangladesh to shut down any undisclosed or additional servers within six weeks and bring all business and financial information under a unified system.
The move is aimed at improving transparency in the insurance sector and strengthening regulatory oversight. According to Mir Nadia Ninvin, chairman of the regulatory authority, a number of insurance companies are not providing regulators with a complete picture of their actual financial and business positions.
She said there were allegations that some companies were maintaining multiple or undisclosed servers to keep separate records of business operations, premium income and other financial activities. Such practices can make it difficult for the regulator to determine the true financial condition and risk exposure of an insurer.
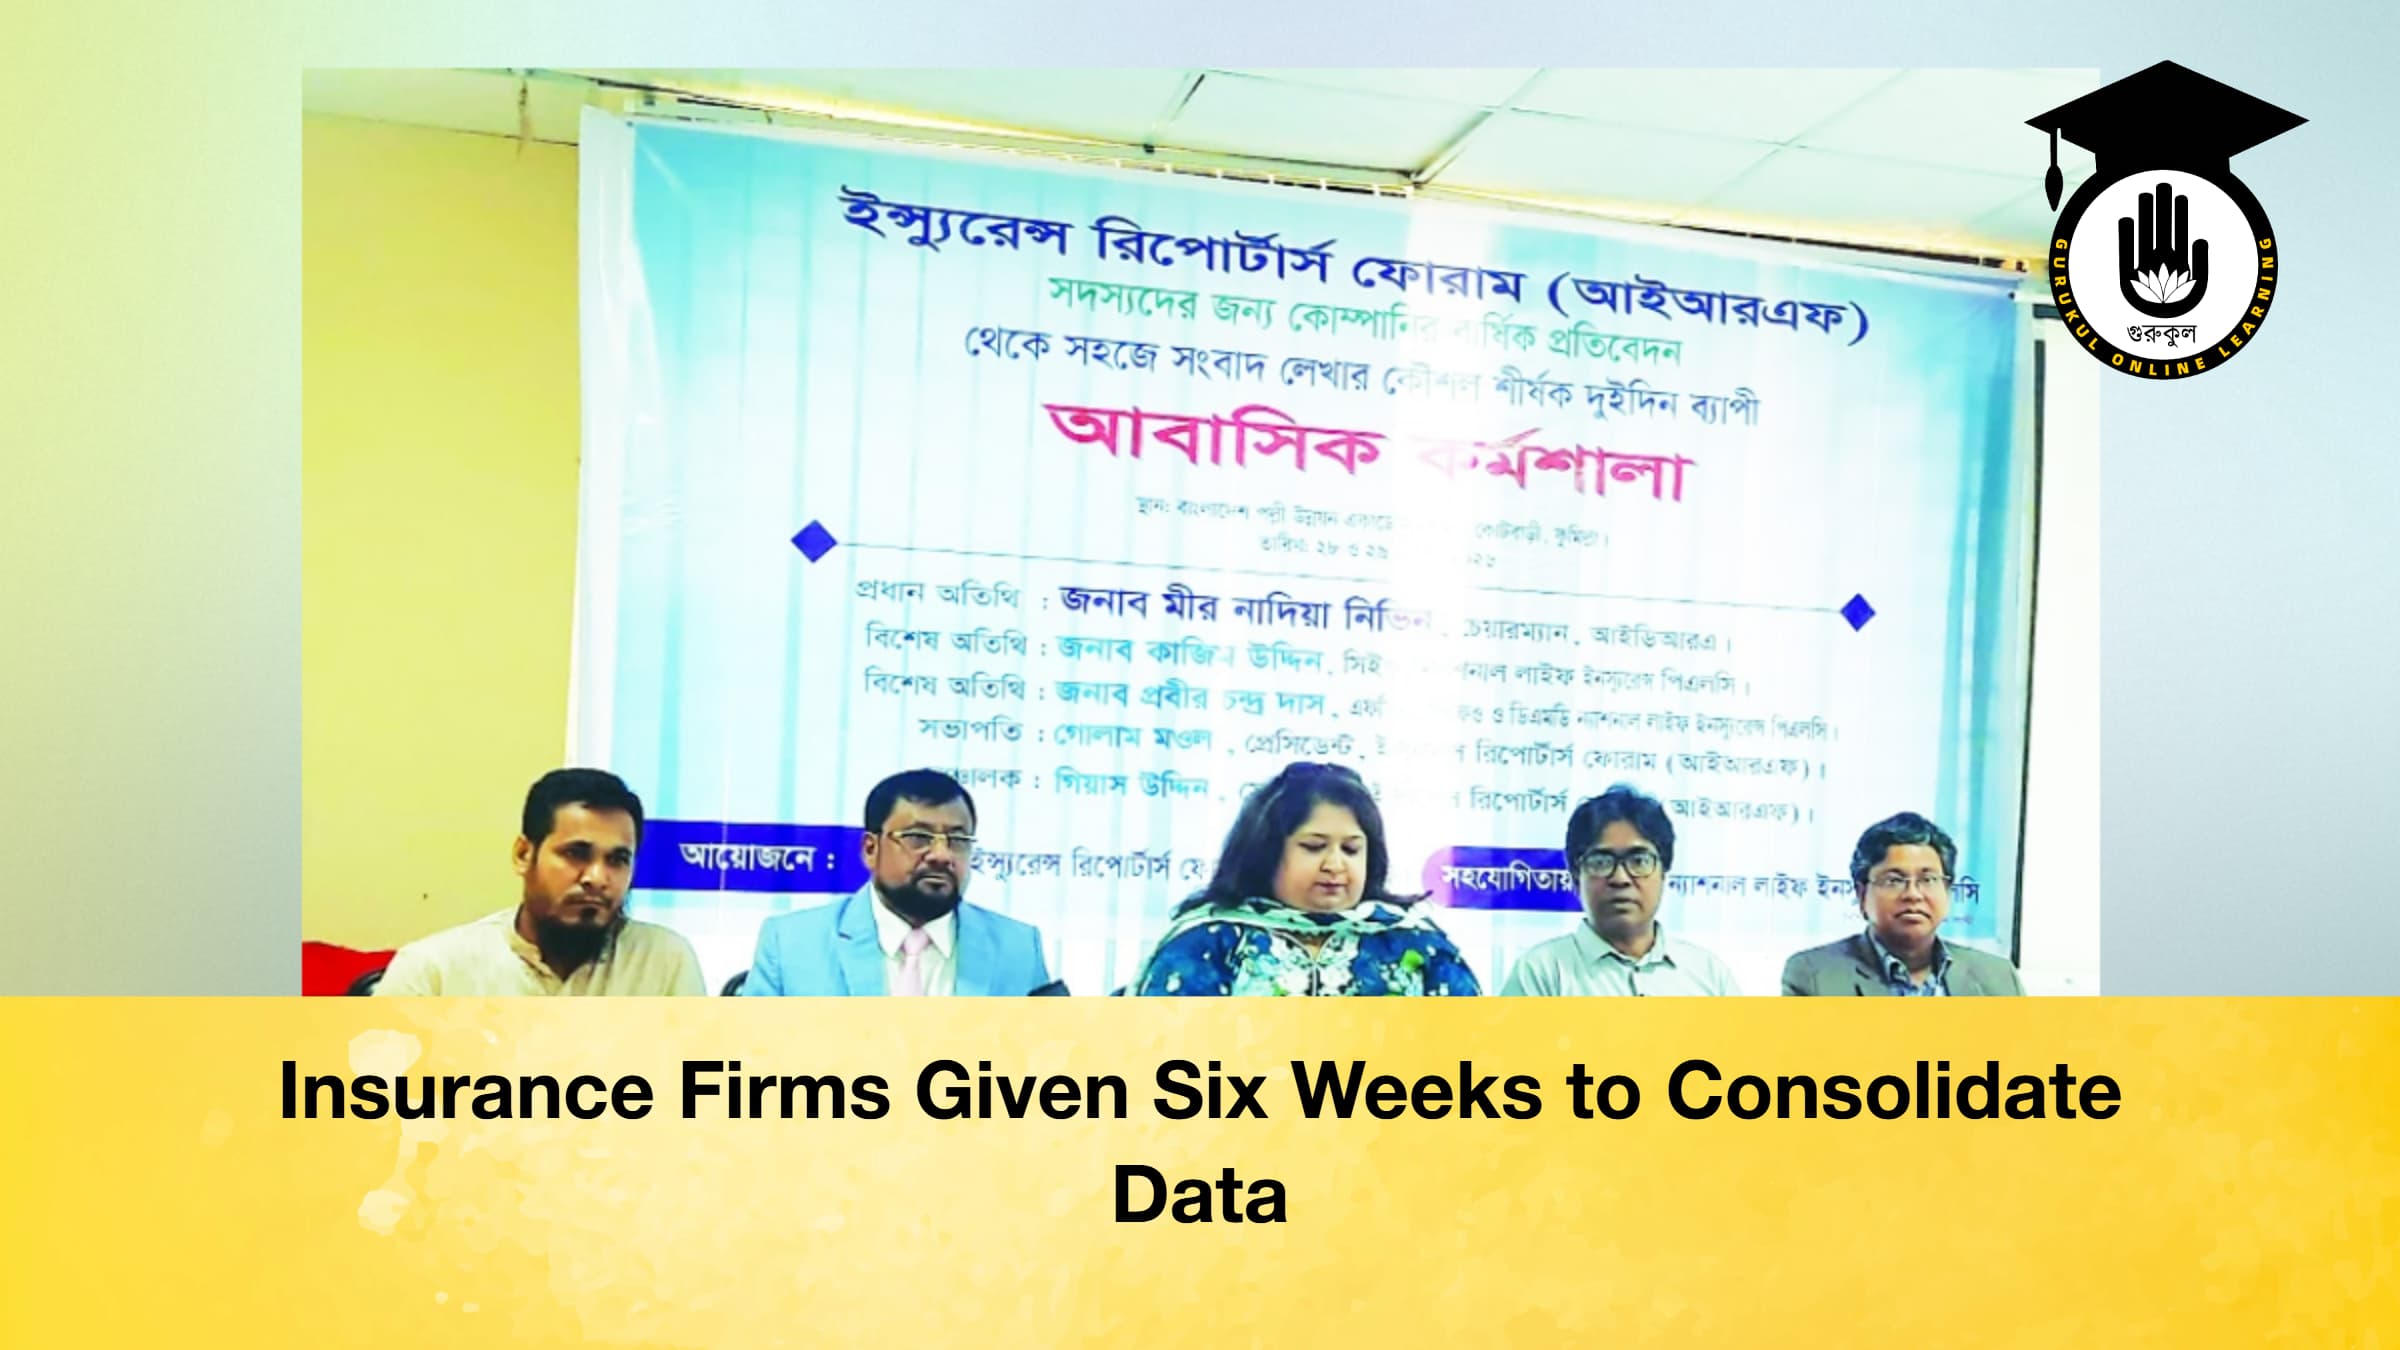
Ninvin made the remarks while inaugurating a workshop organised by the Insurance Reporters Forum at the Bangladesh Academy for Rural Development in Cumilla.
She said discrepancies between information submitted to the regulator and a company’s actual financial position could make it difficult to assess the risks facing the institution. Maintaining business records across multiple servers can further complicate the process, as regulators may not have access to the company’s complete operational picture.
Under the new directive, all undisclosed and additional servers must be shut down within six weeks, while the information stored through different systems must be brought into a consolidated framework.
The chairman also warned that companies failing to comply would face legal action. She said technological audits would be used to identify hidden servers, even if they were kept in garages, underneath beds or in other concealed locations.
Risk-based supervision planned
The regulator is also preparing to introduce a risk-based supervision system by December this year as part of a broader effort to strengthen oversight of the insurance industry.
Ninvin said audited financial statements alone could not always provide an accurate picture of an insurer’s current condition. An audit report may relate to a particular financial year and become available only later. If the information in such a report does not accurately reflect the company’s actual position, regulators may struggle to identify emerging financial weaknesses and risks in time.
Under the proposed system, greater attention will be given to insurers’ financial health, business operations, consistency of submitted information and potential areas of risk.
The approach is expected to shift supervision towards identifying problems based on the level and nature of risk rather than relying solely on periodic financial reporting.
Unique identification numbers for insurance policies
The regulator also plans to introduce a unique identification number for every insurance policy within the next three to four months.
The proposed system would allow individual policies to be identified centrally, making it easier to track policy-related information and verify business records. The authority expects this to reduce the scope for showing fictitious premium income, reporting only part of a company’s business or withholding relevant information.
A separate verification mechanism is also being planned for general insurance.
Under the proposed arrangement, before banks open letters of credit for imported goods, information relating to the relevant insurance cover note would be checked through the regulator’s system. The authority also intends to restrict acceptance of cover notes that do not carry the proposed unique identification number.
Such a system could create a clearer link between insurance coverage, trade-related transactions and regulatory records, making discrepancies easier to identify.
Claims payments planned for customers of troubled insurers
Alongside the regulatory reforms, the authority is preparing to begin paying outstanding claims to customers of several financially distressed insurance companies.
Ninvin said the process would begin next week for customers of seven to eight financially troubled insurers. Money raised through the sale or liquidation of assets belonging to those companies will be used to settle outstanding claims.
The assets include land, government securities and fixed deposits. Funds generated from these assets are being kept in separate bank accounts under the supervision of the regulatory authority and will be used to pay customers who are owed money.
Giving an example of one distressed insurer, Ninvin said the company owed around Tk3,000 crore to its customers. The authority is seeking to raise several hundred crore taka initially by selling land in Feni and liquidating some government securities, with the proceeds intended to support claim payments.
The initiative comes against a backdrop of concerns over delayed settlements and the financial condition of weaker insurers. For policyholders, the ability of an insurer to honour valid claims is one of the most important indicators of confidence in the sector.
Coordination with other government agencies
The insurance regulator also plans to work more closely with Bangladesh Bank, the National Board of Revenue and the Bangladesh Securities and Exchange Commission to strengthen verification of information supplied by insurance companies.
The proposed coordination would allow information held by different government agencies to be compared, making it easier to identify inconsistencies in insurers’ reported business and financial activities.
Such cross-checking could also strengthen regulatory scrutiny by allowing the authority to examine information from multiple official sources rather than depending entirely on records supplied by individual insurance companies.
Ninvin said the regulator currently oversees 82 insurance companies with a workforce of around 150 people. Given the size of the sector and the limited number of regulatory personnel, she stressed the need to strengthen technological capabilities and the legal framework.
The planned reforms therefore place considerable emphasis on centralised information, technological monitoring and closer institutional coordination. Bringing company records into a single system would give regulators a more complete view of insurers’ operations and could make it easier to detect irregularities at an earlier stage.
The six-week deadline for shutting down undisclosed or additional servers is part of this wider effort to improve accountability in Bangladesh’s insurance industry. By consolidating company data, introducing unique policy identification numbers, moving towards risk-based supervision and working with other government agencies on verification, the regulator aims to strengthen oversight while protecting policyholders’ interests.